ASC 606 Commissions: How to Capitalize and Amortize Sales Commissions
TL;DR
Under ASC 606, the revenue recognition standard, and its cost subtopic, ASC 340-40, sales commissions that are incremental costs of obtaining a contract are no longer expensed when paid. They are recorded as a deferred commission asset and amortized as the company delivers the service, which can be longer than the initial contract term if renewals are expected. A practical expedient lets you expense commissions as incurred when the amortization period is one year or less, but it rarely fits multi-year SaaS contracts.
Fixed salaries and company-wide bonuses are not capitalized, while SPIFFs and bonuses tied to specific deals usually are. ASC 606 does not dictate how to design your sales compensation plan, but the plan you choose determines how much accounting work you create. Clear rules on new vs. renewal commissions, clawbacks and other sales incentives keep it clean, and a platform like Driven can automate the schedules and keep them audit-ready.
Revenue recognition rules shape how companies report financial performance, and ASC 606 changed them for every industry. But for sales teams and finance leaders, one of the most practical impacts lands on sales commissions and other sales incentives. When you pay a rep today for revenue you will earn over the next three years, the way you record that cost has real consequences for your financial reporting, your audit and your plan design.
In this guide, we explain what ASC 606 means for sales commission accounting, which incremental costs get capitalized, how to amortize them, how the rules play out in examples, and how your plan design affects the accounting.
This article is for general information and is not accounting advice. Confirm your treatment with your accountant or auditor.
What Is ASC 606? The Revenue Recognition Standard
ASC 606, "Revenue from Contracts with Customers," is the revenue recognition standard issued by the Financial Accounting Standards Board (FASB). Its international counterpart, IFRS 15, was issued by the IASB and is very similar. It took effect for public companies in 2018.
The goal is to create one consistent approach to how companies recognize revenue across industries. Before ASC 606, rules varied by industry, which made companies hard to compare and let some structure a contract to recognize revenue earlier or later. The standard follows a five-step model:
Example: A customer signs a $60,000 two-year contract that includes a software subscription and implementation services. The company allocates the transaction price between the two performance obligations by standalone selling price, recognizes the implementation revenue when the work is done, and recognizes the subscription revenue evenly over 24 months.
The result is that companies recognize revenue as value is delivered, not necessarily when the contract is signed or cash is collected. That timing is exactly why commissions are affected.
Incremental Costs of Obtaining a Contract: What ASC 606 Means for Sales Commissions
Alongside ASC 606, FASB added a subtopic, ASC 340-40, on the costs of obtaining and fulfilling a contract with a customer. For sales commissions, the rule is:
ASC 340-40 in short: Incremental costs of obtaining a contract, such as sales commissions, must be recorded as an asset if the company expects to recover them. That asset is then amortized as the related goods or services are delivered.
An incremental cost is a cost you would not have incurred if the contract had not been won. A commission on a signed contract is the textbook example: no deal, no commission. Identifying the incremental costs of obtaining a contract correctly is the first and most important step in sales commission accounting, and only incremental costs of obtaining a contract with a customer are capitalized. Other costs of selling are expensed.
Before ASC 606, many companies recorded commissions as an expense when they were earned or paid. Now, if a rep earns a commission on a three-year contract, you capitalize it and spread the expense over the period you benefit from that contract. This matches the cost to the revenue recognition pattern of the contract and the future revenue it helps generate, and it avoids a spike of expense in the period a burst of deals closes, which would otherwise distort short-term results during rapid sales growth.
A few terms you will see:
- Capitalize: record the cost as an asset on the balance sheet instead of an expense on the income statement.
- Deferred commission (or deferred sales commissions): the deferred asset that holds capitalized costs of commissions.
- Amortize: gradually move the asset to expense over time.
Commissions are classified as selling expenses (part of SG&A), not cost of goods sold.
Deferred Commission vs. Deferred Revenue
These two are easy to mix up, and they are opposites. A deferred commission is an asset: you paid, or owe, a cost to win a contract and have not yet used up its benefit. Deferred revenue is a liability: a customer paid you before you delivered, so you owe them the service. Both are spread over time, but they sit on different sides of the balance sheet.
Key Takeaway: ASC 606 changes when commission expense reaches the income statement, not how much you pay your reps. It does not change the structure of sales compensation plans, but, as we will see, plan design affects how complex the accounting becomes.
For the authoritative guidance, see Deloitte's roadmap on costs of obtaining a contract and PwC's guide on incremental costs of obtaining a contract.
Which Incremental Costs Get Capitalized (and Which Don't)?
Only incremental costs of obtaining a contract qualify, and only if the company expects to recover them. All other costs incurred, such as general selling costs, are expensed as incurred. The dividing line is the link to a specific signed contract.
Costs incurred whether or not a contract is signed are never incremental. A commission on a signed contract is incremental. A quarterly bonus based on company revenue is not, because it would be paid whether or not any individual contract was signed. And a commission that is paid only if the rep stays employed (a requirement of future service) is treated as compensation over that service period, not as a cost of obtaining the contract. For most SaaS commissions, recoverability is straightforward, because the contract value exceeds the commission.
Payroll Taxes and Fringe Benefits
Employer payroll taxes and other related costs on a capitalized commission, such as fringe benefits, are generally capitalized with it. Accounting teams often miss them, because they sit in a different system from the commission data. If you capitalize a $6,000 commission, the payroll taxes on that commission follow it into the deferred asset and are amortized over the same period.
How to Capitalize and Amortize Sales Commissions
Here is the process, step by step:
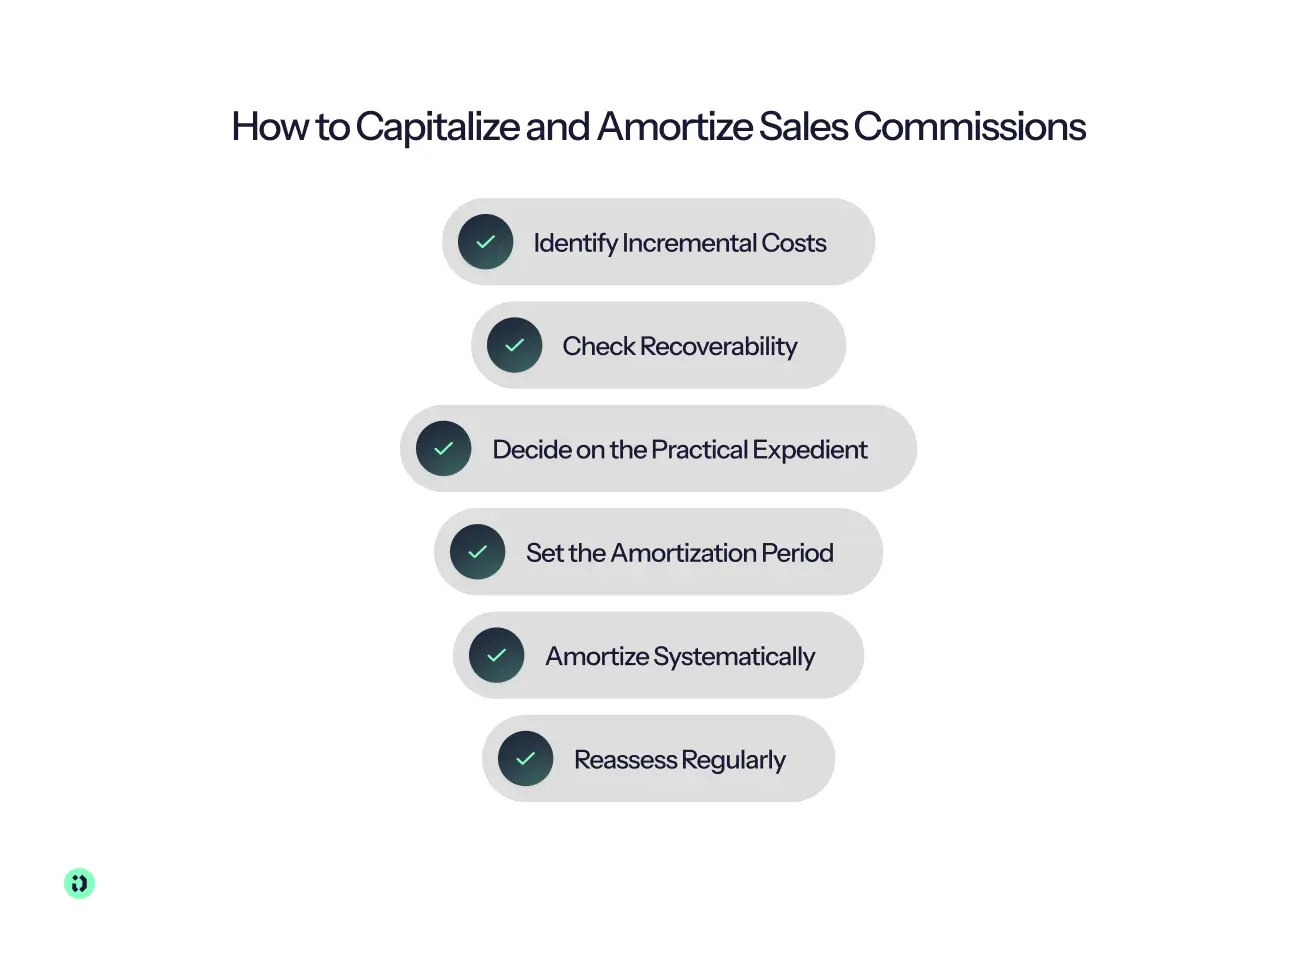
- Identify Incremental Costs: For each signed contract, identify the incremental costs of obtaining the contract: the commission payments, SPIFFs, overrides and related costs that would not exist without it.
- Check Recoverability: Confirm you expect to recover the capitalized costs from the margin on the contract. Capitalized costs that cannot be recovered are not eligible.
- Decide on the Practical Expedient: If the amortization period is one year or less, you can choose to expense the incremental costs as incurred (see below).
- Set the Amortization Period: Estimate the expected period over which the customer benefit is transferred.
- Amortize Systematically: Spread the expense in a pattern consistent with how you deliver the service, typically straight-line, monthly or quarterly.
- Reassess Regularly: Review the asset when contracts change, customers churn or expectations shift.
How Long Is the Amortization Period?
The amortization period is the hardest judgment. The standard says to amortize on a systematic basis consistent with the transfer of the goods or services the asset relates to, and the amortization period may exceed the initial contract term.
The key question is anticipated renewals. If you pay a lower commission on contract renewals than on the initial sale (for example, 10% on the first contract and 2% on renewals), the initial commission is not "commensurate" with the renewal commission. That suggests the initial commission also benefits the renewal periods, so you may need to amortize it over the expected period of the customer relationship, including anticipated contract renewals. If the renewal commission is commensurate with the initial one, each is amortized over its own term.
To support the period, look at your historical data: average customer lifetime, churn and renewal rates. Auditors will expect a defensible basis. Some companies apply the guidance to a portfolio of contracts with similar characteristics instead of contract by contract, if the result would not differ materially.
The One-Year Practical Expedient
ASC 340-40 allows a company to expense commissions as incurred if the amortization period would be one year or less. This practical expedient comes with a few conditions:
- It is an accounting policy election, applied consistently to similar contracts. You cannot choose it on a contract by contract basis.
- It is useful for short contracts, and for commission payments that relate to a short benefit period.
- It rarely applies to multi-year SaaS contracts, especially once anticipated renewals extend the amortization period beyond a year.
Put Your Policy in Writing
Document how your company handles this, so it is applied the same way every period and supports consistent financial reporting:
- Which incremental costs are capitalized, and which costs incurred are expensed
- The amortization periods and the basis for them
- Treatment of renewals, expansions and modifications
- Adjustments for churn, cancellations and clawbacks
- Whether the one-year practical expedient is elected
Examples with Journal Entries
Here are three scenarios showing how incremental costs of obtaining a contract are capitalized and amortized. The amounts are illustrative, and the exact entries depend on your chart of accounts and policy.
Example 1: Upfront Commission on a Three-Year Contract
- Contract term: 36 months
- Commission paid: $6,000
- Amortization period: 36 months (assume no difference between initial and renewal commissions)
- Monthly amortization: $6,000 ÷ 36 = $166.67
Even if the rep receives the full $6,000 commission payment immediately, you recognize the expense over three years.
Example 2: Journal Entries on a Two-Year Contract
A customer signs a 24-month contract worth $60,000. The rep earns 8% of the contract value, which is $4,800. The amortization period is 24 months.
At signing (commission earned and capitalized):
Every month for 24 months ($4,800 ÷ 24 = $200):
After 24 months, the deferred asset is zero, and the full $4,800 of deferred sales commissions has been matched to the revenue recognition pattern of the contract.
Example 3: A Lower Renewal Commission
A customer signs a 12-month contract worth $12,000. The rep earns 10% ($1,200) on the initial sale and 2% ($240) when the customer renews. Historical data shows customers typically stay for three years.
- Because the renewal commission is much lower than the initial one, the initial $1,200 may need to be amortized over the expected 36-month customer life: $1,200 ÷ 36 = $33.33 per month.
- The $240 renewal commission, if it is incremental, is amortized over the renewal term when the customer renews.
This is the kind of judgment that needs documentation and, ideally, accountant sign-off.
A Note on Commissions Paid Monthly
Some plans pay commission each month as the customer pays, for service delivered in that same month. Because the benefit period for each commission payment is short, many companies expense these as incurred under the one-year practical expedient, if they have elected it. This is often the simplest structure from an accounting perspective, but check the treatment with your accountant, since it depends on how the commission is earned and on your policy.
Calculating amortization schedules for deferred sales commissions by hand across dozens of reps and multiple contracts is where accounting teams lose days. With Driven, capitalization and amortization schedules are calculated automatically from your commission data, so the journal entries are ready when the period closes and your financial reporting is accurate.
How Commission Plan Design Affects the Accounting
ASC 606 does not tell you how to design your sales compensation plan. But the way you design it determines how much accounting complexity you create, which is why aligning sales compensation with revenue recognition timing is a design decision, not just a finance one. Here is how common plan features play out:
Three practical design principles help:
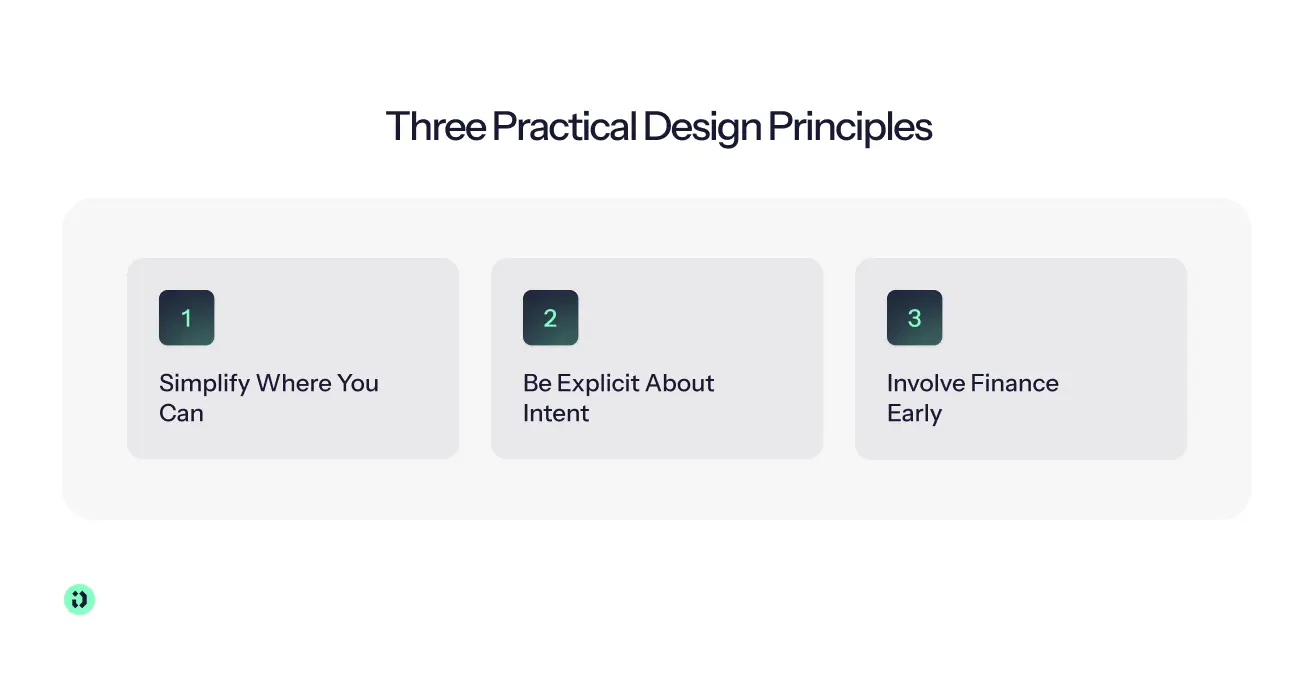
- Simplify Where You Can: A plan with fewer types of sales incentives, such as fewer SPIFFs and bonuses, is easier to account for and easier for reps to understand.
- Be Explicit About Intent: For every bonus or SPIFF, state whether it is tied to specific contracts. Auditors look at intent.
- Involve Finance Early: Sales leaders, RevOps and finance leaders should agree on the plan and the accounting treatment together. Review the plan before you launch it, not after the first audit.
Before rollout, Driven lets you test a plan against historical payouts, so sales and finance can see how it would pay out and what it means for the schedules.
Renewals, Modifications, Clawbacks and Early Termination
Contracts change, and every change can touch the capitalized asset. Here are the cases to plan for:
- Renewals and expansions: Evaluate each renewal commission to decide whether it is incremental, and whether its treatment lines up with the initial commission. A renewal commission can be capitalized if it is incremental and recoverable. Each time a customer renews, a new layer of asset appears, with its own amortization period.
- Contract modifications: Upgrades, downgrades and added seats are accounted for as a separate contract, a termination and a new contract, or part of the same contract, depending on whether the changes are distinct.
- Early termination: If a customer cancels earlier than expected, the remaining asset may need to be accelerated or written down.
- Impairment: If the asset's carrying amount exceeds the future revenue you still expect to receive from the contract (less the costs to deliver it), you recognize an impairment loss.
- Clawbacks: If a rep returns a commission because of a cancellation, the asset and the amortization schedule need to be adjusted.
Each of these is manageable once, and a growing problem across hundreds of customer contracts. Driven tracks contract changes, renewals and expansions in the same system as the commission data, so schedules are updated without rework.
How Driven Helps with ASC 606 Commission Accounting
Driven is the AI-powered sales commission platform that automates commission calculations, tracking and payouts, and keeps the accounting side in the same place. It replaces the spreadsheets, the manual reconciliations and the guesswork with a single source of truth that sales teams and finance leaders can both trust.
Driven includes a dedicated ASC 606 compliance module that lets finance teams:
- Automatically capitalize and amortize commissions across contracts and periods
- Maintain audit-ready schedules and documentation
- Sync commission data with revenue recognition workflows
- Track contract changes, renewals and expansions without manual work
What Auditors Expect to See
Whatever tool you use, auditors usually look for the same evidence each period:
- A schedule by contract: the commission capitalized, the amortization period and the amortization recorded
- A roll-forward of the deferred commission balance: opening balance, additions, amortization and any write-offs or impairment
- Your written policy: including the basis for the amortization period and whether the practical expedient is elected
- A reconciliation to the general ledger: so the schedule ties to the financial statements
- Support for each commission: a link to the signed contract and the payout calculation
Driven keeps this evidence in the same place as your commission calculations, so it is there when the audit starts instead of rebuilt afterward.
"We went from spending 3 days on commission calculations to getting it done in 3 hours. Driven gave our reps real-time visibility into their earnings, which was a game-changer for our team." – Thijs Janse, SVP Revenue, Aikido Security
Whether you are a SaaS company with multi-year contracts or a business with complex sales incentives, the goal is the same: one system, one set of numbers, and a compliance process that does not depend on someone's spreadsheet.
See your comp plan, fully built in minutes
Frequently Asked Questions
About the author


- What they do: AI tools for sales operations take repetitive work off your team, keep CRM data clean and surface insights across planning, routing, forecasting and pay.
- The main lesson: match the kind of AI to the job. AI drafts, explains and flags; fixed rules calculate anything involving money or ownership; a human signs off.
- Best AI tools for sales ops: Driven (compensation), Fullcast (territory and quota planning), Clay (data enrichment), LeanData (lead routing), Gong (pipeline and forecasting).
- What's at stake: real teams lose from one or two days to two weeks per quarter on manual work.
- How to choose: start from your CRM, fix your source of truth, pick the one bottleneck that hurts most and test edge cases in a pilot.
- Sales commission automation is the process of using rules, data, and automated systems to calculate, track, approve, and report sales commissions with less manual effort.
- You can automate sales commissions with spreadsheets, build a custom system, or use dedicated sales commission software, depending on your team's size, commission structures, and business needs.
- A useful rule of thumb is: AI can help draft and explain plans, rules should calculate payouts, and humans should approve them.
- To get started, identify your source of truth, clean your CRM and sales data, document your commission rules, and then choose the automation approach that fits your commission process.
- Aikido Security used Driven to cut its commission processing time from 3 days to 3 hours, while giving 120+ sales reps real-time visibility into their earnings.
Most commission plans fail because nobody modelled the numbers before rolling them out. A rate that looks generous on a slide turns into a payout you can't afford at 130% attainment, or an accelerator so flat that your best sales reps stop pushing the moment they hit quota.
So we collected the eight most common sales commission structures into a single free commission sheet template. It is one workbook with a commission spreadsheet for each structure, each with live formulas and a filled-in example. Change a rate, a quota, or a revenue number and every payout updates instantly, so you can compare sales commissions across models in one place.
Open the template in Google Sheets or start for free and let Driven build the plan for you.

Sales performance analysis is the process of examining sales data to understand what is driving results, what is holding them back, and what to change next. It differs from reporting, which only says what happened, and the ongoing practice and technology behind it is called sales analytics.
A good sales analysis starts with a clear question, tracks a handful of key sales metrics (win rate, conversion rate, average deal size, sales cycle length, quota attainment, pipeline coverage and cost of sales), and looks at the data through five lenses: time, rep, territory, customer segment and lead source. The practical process has seven steps: ask a question, collect the sales data, clean it, set a baseline, identify trends through the lenses, diagnose the root cause, and act and monitor.
To evaluate individual sales reps, use a balanced scorecard of outcomes, activity and quality, and look at how attainment is distributed across the team, not just the average. Because compensation shapes behavior, it helps to analyze pay against performance too.
Driven acts as the data layer that connects your CRM and commission data, so you can query it in natural language and build the dashboards each person needs.
A SPIF (Sales Performance Incentive Fund, also spelled SPIFF) is a short-term sales incentive that rewards sales reps for a specific goal within a defined period, such as selling a specific product or hitting a revenue milestone. It sits on top of sales commissions and is usually paid out fast, which is what makes it effective.
Every SPIFF works the same way: set a goal, define the reward, set a timeframe, track performance, and pay out quickly. SPIFFs come in several types, including individual, team, product, tiered, activity-based, and vendor-funded, and sales teams use them to focus attention, create urgency, and boost sales. To build an effective SPIFF program, define the objective, write simple rules, set a budget, and communicate clearly. To measure one, compare results to a baseline and check the cost per extra sale. The most common mistakes are overcomplicated rules, running SPIFFs too often, and rewards too small to matter. Tools like Driven automate the tracking and payouts, so none of this lives in a spreadsheet.
Incentive pay is variable pay that rewards employees for results, paid on top of base pay and earned again in each period. It counts toward total earnings and is generally taxable, but it is not part of the fixed salary.
Common types include commission, performance bonuses, team incentives, gainsharing, profit sharing, spot awards, non-monetary incentives, and long-term incentives like stock options. Unlike a bonus, which rewards past results, or merit pay, which is a permanent raise, incentive pay is agreed in advance and drives future performance.
It is calculated as a performance result multiplied by an incentive rate, using flat, threshold, tiered, or target-based structures. To make it work, set clear objectives, use a few meaningful metrics, set realistic targets, and pay out accurately and on time with transparent statements.
The main risks are gaming, sandbagging, short-term focus, and perceived unfairness, and clear data and automation help catch them early.
A sales compensation plan defines how your sales team gets paid: a fixed base salary, variable pay like commissions and bonuses, and a quota that decides how much of that variable pay a rep actually earns. Base salary plus target variable pay makes up a rep's on-target earnings (OTE).
Sales compensation plans do more than pay people; they shape behavior, drive revenue, and define culture. Get the plan right, and your team is aligned, motivated, and chasing the numbers that actually matter. Get it wrong, and you'll spend every month-end on disputes, recalculations, and reps who no longer trust their payslip.
This guide covers the core components, the main plan types, and a 10-step process to build your own, followed by three sales compensation plan examples. Jump to the examples. Everything here draws on Driven's work with finance, RevOps, and sales compensation leaders who run these plans every single month.
Sales commission software calculates, tracks and explains commissions from your CRM data, so nobody rebuilds a spreadsheet every month. The 9 best tools in 2026:
- Driven: best AI commission agent for HubSpot and Salesforce teams that want to go live in days
- QuotaPath: best for growing teams that want published pricing and broad CRM coverage
- CaptivateIQ: best for mid-market teams with complex, frequently changing plans
- Salesforce Spiff: best for companies that run on Salesforce
- Qobra: best for European RevOps teams that want no-code plans and AI agents
- Xactly Incent: best for large enterprises that also need planning and forecasting
- Performio: best for complex crediting across many data sources and regions
- Sales Cookie: best for small businesses that want month-to-month contracts
- QCommission: best for finance-led teams on QuickBooks or needing on-premise deployment
Choose based on three things: your CRM, how many reps you pay, and how complex your plan is.
TL;DR: Salesforce stores every field commissions depend on, but core Sales Cloud doesn't calculate, explain or protect payouts. Teams close that gap in one of five ways: native formula fields, a custom build, Salesforce's native ICM (Spiff), a vibe-coded tool, or a third-party commission tool. A flat rate and a few reps can stay native. Tiers, accelerators, splits and frequent plan changes point to a dedicated tool, and to an agentic platform like Driven if you want the plan designed, explained and maintained for you.
It's not uncommon for teams in 2026 to still run sales commissions on spreadsheets. The deal data lives in Salesforce, the rates live in a Google Sheet someone built three finance leads ago, and the payouts get reconciled by hand at the end of every quarter. When a rep asks why their number looks different, no one can fully explain it. When finance needs an accrual, someone exports a report and rebuilds it in Excel. The process is time-consuming, error-prone, and actively eroding rep trust. It's hard to keep a sales team motivated when reps can't trust their own paycheck.
Teams that outgrow the spreadsheet usually reach for formula fields, a custom build, or a paid add-on. But tools for managing sales incentives are now moving from rules engines you configure to agents that work alongside you. Gartner predicts that 40% of enterprise applications will feature task-specific AI agents by the end of 2026, up from less than 5% in 2025. They also say that 60% of B2B seller work will be executed through conversational interfaces by 2028.
This guide breaks down five ways to track Salesforce commissions, including what each approach does well, where it breaks, and how to choose.
To calculate sales commission, multiply the commissionable sales amount by the commission rate. A $40,000 sale at 8% earns $3,200. Base-plus-commission plans add that figure to salary, and tiered plans apply each tier's rate only to the sales inside it. The hard part is agreeing which deals count and what the rate applies to.
Three core formulas cover almost every plan. Straight commission is Commission = Sales × Rate. Base plus commission is Total pay = Base salary + (Sales × Rate). Tiered commission adds up each tier separately: (Tier 1 sales × Tier 1 rate) + (Tier 2 sales × Tier 2 rate), and so on for every tier the rep reaches.
This guide shows why most payout errors come from deciding which deals count rather than from the calculation itself. It explains why tiered plans can pay very different amounts depending on whether tiers are marginal or retroactive, and it covers why payouts should be locked once approved, so later CRM changes don't alter what has already been paid.

Ask a sales rep what's driving their next paycheck, and you'll often hear all three words used interchangeably: SPIFF, bonus, and commission. They get lumped together as "extra money for selling," but they're not the same thing, and treating them like they are leads to confused reps, inconsistent payouts, and comp plans nobody can actually explain.
A SPIFF is a short-term, targeted incentive. A bonus is a lump-sum reward tied to hitting a broader goal. A commission is the ongoing, formula-based pay tied directly to sales, the core of most sales comp plans, not an add-on to it.
This guide breaks down what each one actually means, when companies use them, how they're calculated, and how they stack together so you can build a comp plan where every payout has a clear reason behind it.

New sales hires often get offered a "draw" against commission, and most sign the offer letter without knowing there are two very different types. That gap in understanding can mean thousands of dollars either staying in a rep's pocket or getting clawed back months later.
A draw is essentially an advance on future commission, designed to give reps steady income while they ramp up pipeline and close their first deals. But whether that advance is recoverable or non-recoverable determines something much bigger: whether it ever has to be paid back.
This guide breaks down what each draw type means, how they're calculated, when companies typically use each one, and the mistakes that turn a helpful ramp tool into a trust problem between reps and the company that hired them.
Not every sales role drives revenue the same way, so it doesn't make sense to pay everyone on the same plan. Yet plenty of companies still try to copy-paste one commission structure across the whole sales org, and then wonder why half the team feels underpaid and the other half feels unmotivated.
Sales Development Representatives (SDRs) generate qualified pipeline. Account Executives (AEs) close it. Their responsibilities are different, their quotas are different, and their performance metrics are different, which means their compensation plans need to be different too.
In this guide, you'll learn the key differences between SDR and AE roles, how their compensation plans are typically structured, common pay mixes and incentive models, mistakes companies should avoid, and how compensation software makes managing both plans easier as a team grows.
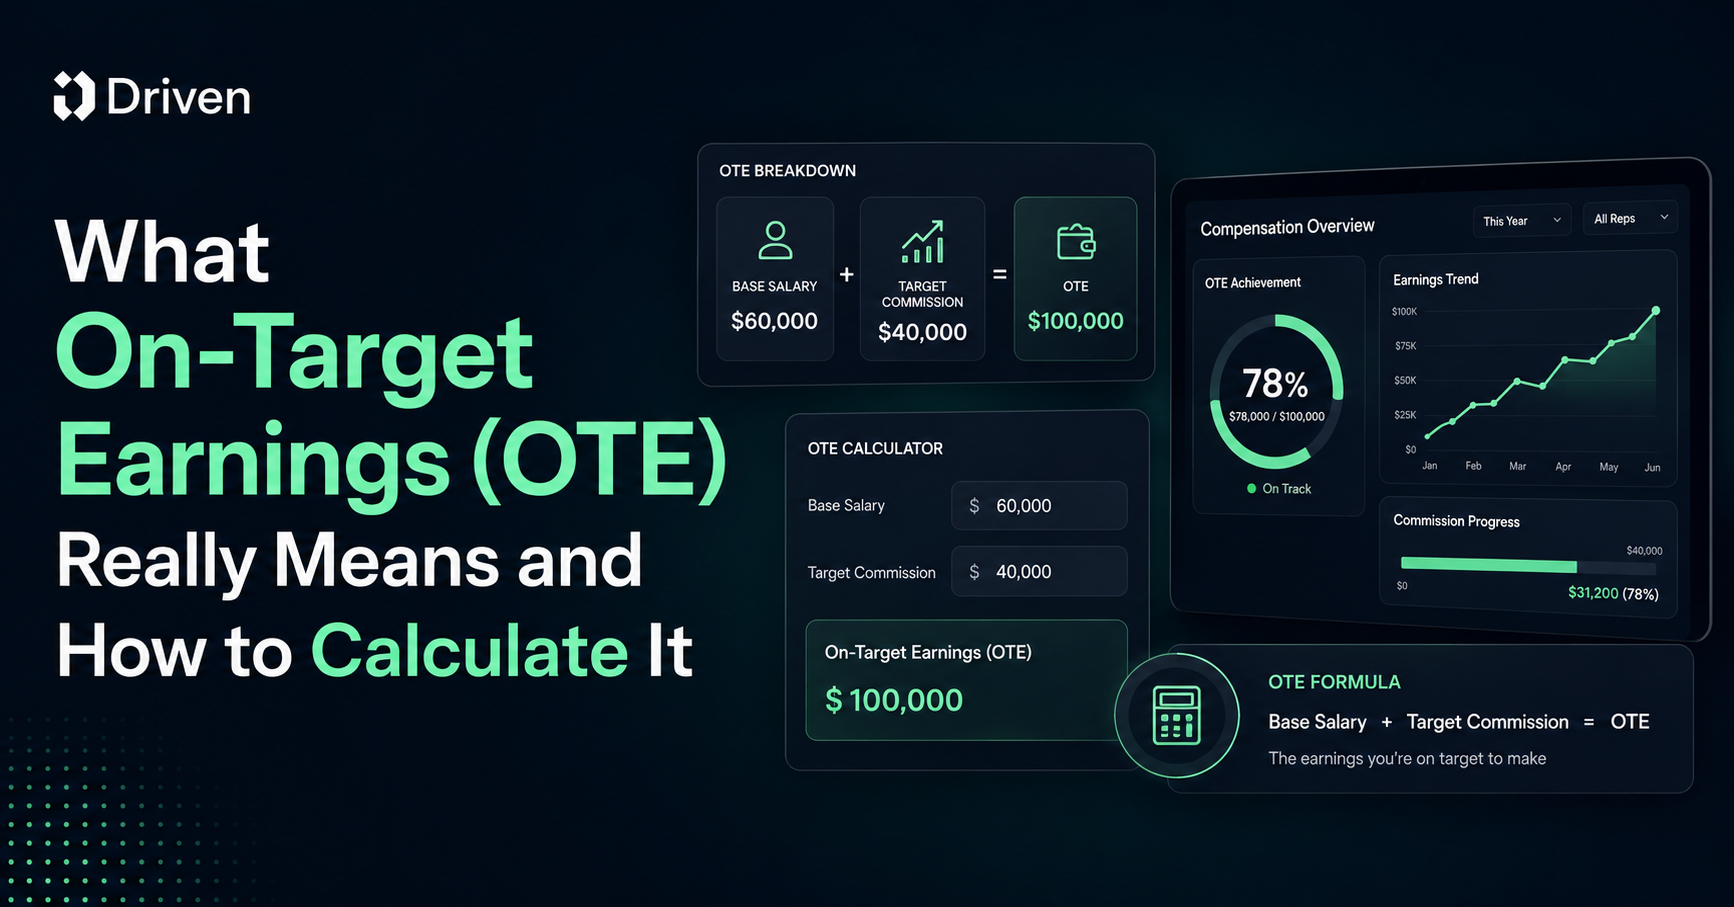
Ask ten sales reps what OTE means and you'll get ten different answers. Some think it's their salary. Some think it's guaranteed. Some think it's a number recruiters made up to make a job posting look better than it is.
On-Target Earnings, or OTE, is one of the most misunderstood terms in sales compensation, and that confusion costs people real money and real trust. Candidates accept offers they don't fully understand. Reps hit quota and still feel confused about their paycheck. Finance teams build comp plans that nobody on the floor can explain in one sentence.
This guide breaks down exactly what OTE means, how to calculate it, and how it's different from base salary and total compensation. You'll walk away knowing how to read an offer letter, build a comp plan, or explain your own earnings potential without the guesswork.
Revenue Operations has become the foundation of modern revenue teams in 2026. What once focused mainly on aligning sales and marketing now connects every revenue-related function, workflow, and process across the organisation. However, many companies still struggle with disconnected tools and fragmented systems. Businesses invest in CRMs, forecasting platforms, analytics software, customer success tools, and compensation management systems, but often end up with siloed data and inefficient workflows.
As a result, teams spend more time fixing operational issues than driving growth. A successful RevOps tech stack is not about having more software, it’s about ensuring every tool works together seamlessly. In this guide, we’ll explore how to build a connected RevOps stack that improves visibility, automation, and operational efficiency while reducing complexity. We’ll also look at how platforms like Driven help automate commission operations with AI-powered workflows.
Sales compensation has moved from a back-office payroll function to one of the most strategically important levers a revenue organisation can pull. For RevOps leaders, compensation data isn't just interesting; it's operational intelligence. The right benchmarks reveal whether your quota structure is realistic, whether your commission model is driving the right behaviours, whether your reps trust the plan they're working under, and whether your finance team is spending 40 hours a month on a process that should take four.
In 2026, the data tells a clear story: most organizations are underperforming on compensation design, overspending on manual administration, and underinvesting in the transparency that keeps sales teams engaged and motivated. This guide compiles the most important sales compensation statistics. RevOps leaders need to know this year and translate each data point into a practical implication for strategy and execution.
A sales team's compensation structure directly influences performance, motivation, retention, and revenue growth. When designed correctly, it encourages the right behaviors, rewards top performers, and aligns sales activities with business goals. When designed poorly, it can create confusion, reduce motivation, and drive unwanted behaviors.
Whether you're building your first sales team or refining an existing compensation plan, understanding sales compensation structures is essential for long-term success.
If you’ve spent any time around startups, scaling companies, or even corporate teams, you’ve probably heard the term “Ops” thrown around in meetings, job titles, or strategy discussions. Sales Ops, Marketing Ops, RevOps, DevOps, it’s everywhere. But what does “Ops” actually mean in business? And more importantly, why has it become such a critical function for companies that want to grow efficiently.
The truth is, most businesses don’t struggle because they lack ideas or demand. They struggle because things break internally, processes are unclear, teams are misaligned, and execution becomes messy. That’s where Ops comes in. In this guide, we’ll break down what Ops really means, what it includes, and why it plays a central role in building a scalable, high performing business.

Most companies think they have a compensation problem. They don't; they have an alignment problem. Sales teams focus on what they’re paid to do, while leadership focuses on revenue growth, predictability, and profitability. When those priorities aren’t tightly connected, things start to break quietly at first, then all at once. Revenue targets are consistently missed, payouts increase without meaningful impact, and reps begin optimizing for incentives instead of outcomes.
Here’s the uncomfortable truth: if your compensation plan isn’t directly tied to revenue goals, it’s working against you. If you want to understand where sales compensation is heading, explore our take on the future of sales compensation.

In today’s performance driven business environment, companies are moving beyond fixed salaries and embracing compensation models that directly reward results. Variable incentive pay has become a cornerstone of modern compensation strategies, especially for sales and revenue teams. But while the concept sounds simple, designing an effective variable pay plan is anything but.
Done right, it can drive performance, boost motivation, and align teams with business goals. Done poorly, it can create confusion, mistrust, and missed targets. In this guide, you’ll learn what variable incentive pay is, the different types, its key benefits, and how to design plans that actually work in 2026 and beyond.
You can build a highly data driven, strategically aligned compensation plan and still see it fall apart within weeks of rollout. The reason is simple: your sales team may not fully understand it, trust it, or believe they can actually succeed under it. When reps feel uncertain about how they earn, even the best designed plans lose their impact.
In 2026, success in sales compensation isn’t just about plan structure or incentives; it's about how clearly and consistently changes are communicated. Sales teams today are more informed, more analytical, and more sensitive to fairness than ever before something closely tied to trends shaping the future of sales compensation and how AI is changing the game. When communication falls short, confusion grows and motivation drops. This blog breaks down how to communicate compensation plan changes in a way that builds clarity, trust, and adoption rather than resistance.

A sales commission plan is meant to motivate your team—but when it’s poorly designed or misaligned with business goals, it becomes a silent revenue killer. Many companies underestimate how much damage a flawed compensation structure can cause because the problems don’t appear all at once. Instead, they compound quietly over months: reps chase the wrong deals, turnover increases, disputes rise, and forecasting becomes unreliable.
Meanwhile, leadership often looks everywhere except the comp plan to diagnose performance issues. The truth? Your commission structure has more influence over revenue growth, morale, and productivity than almost any other operational system. When incentives are unclear or unfair, even your best sellers give up. And when incentives are aligned and transparent, the entire organization accelerates. In this post, we break down the hidden financial costs of a poorly designed commission structure and how modern compensation systems are helping revenue teams eliminate those risks altogether.
Sales teams are the backbone of any revenue-driven organization, but even the most talented reps can underperform without the right incentives. A well-crafted sales compensation plan doesn’t just pay your team; it motivates, aligns, and drives consistent, high-level performance. Too often, companies rely on outdated spreadsheets, unclear quotas, or one-size-fits-all commission structures, leaving reps frustrated and sales results inconsistent.
In today’s competitive market, designing a compensation plan that balances fairness, transparency, and ambition is essential. This guide walks you through a tactical approach to building plans that reward the right behaviors, keep reps motivated, and ultimately help your business hit and exceed its revenue goals.

In today’s competitive business environment, sales teams need more than just enthusiasm and product knowledge; they need direction, focus, and measurable goals. This is where Management by Objectives (MBO) comes into play.
MBO isn’t just another management buzzword; it’s a proven approach that helps organizations align their goals with individual performance. By setting clear, achievable objectives, MBO transforms how sales teams operate, helping them stay focused on what truly matters, driving results. But what exactly is MBO, and how can it revolutionize your sales strategy? Let’s explore in depth.
Sales compensation software has moved far beyond spreadsheets and manual commission tables that are prone to errors, delays, and confusion. Modern compensation platforms now help businesses design fair and motivating compensation plans, automate even the most complex commission calculations, accurately forecast payout costs, and improve transparency across the entire sales organization. By providing real-time visibility into earnings and performance, these tools keep sales teams motivated while helping finance leaders maintain control over budgets and revenue planning. In a world where sales velocity, scalability, and revenue predictability matter more than ever, choosing the right sales compensation software can truly transform how your revenue organization operates and grows.
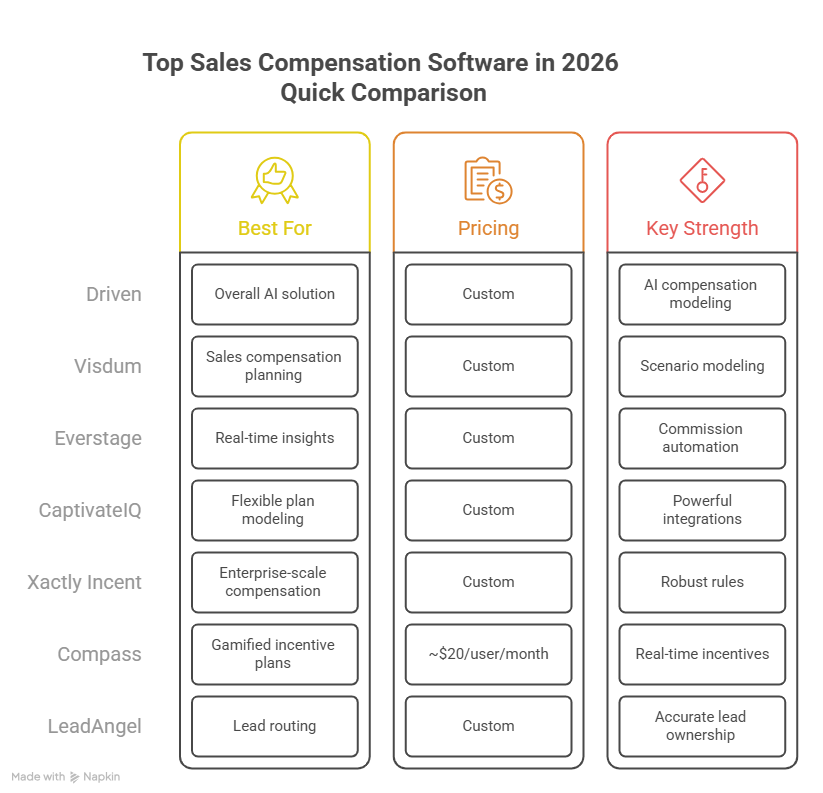
In this guide, we review the best sales compensation software available today, compare their key features, pricing models, and ideal use cases, and help you confidently choose the platform that best fits your business goals.

In today’s competitive business environment, achieving consistent sales growth is a challenge. Organizations often face real challenges when it comes to keeping sales teams motivated, tracking performance accurately, and making sure everyone’s efforts support the company’s bigger goals. Sales Performance Management (SPM) helps bring clarity to all of this. Instead of just offering tools, SPM provides a structured, fair way to evaluate performance, reward the right people, and strengthen the entire sales process so revenue grows consistently.
In this blog, we’ll explore what SPM is, why it matters, its core functions, the benefits it brings, the risks of operating without it, and how to choose the right SPM solution for your business.
If youʼve ever tracked commissions in a spreadsheet, you know how messy it can get, late nights fixing formulas, endless back-and-forth with sales reps, and disputes that eat into everyoneʼs time. What feels “cheap and easyˮ at first quickly turns into a drain on productivity and trust. On top of that, most salespeople donʼt fully understand their complex compensation plans when theyʼre buried in Excel formulas, which only adds to the confusion. Automated sales compensation software solves both problems: it not only removes errors but also clarifies commission plans so reps know exactly how theyʼre being paid.
And the numbers back this up: studies show that nearly 9 out of 10 spreadsheets contain errors. For something as critical as sales compensation, even a small mistake can cost thousands of dollars, spark disputes, and leave reps questioning their pay. The reality is simple: manual commission tracking isnʼt just inconvenient, itʼs costly. In this blog, weʼll uncover those hidden costs, compare manual vs automated commission tracking, and explore how automation transforms commission management from a constant headache into a driver of growth and transparency.